The "Election Effect" of Bitcoin: Political Catalyst or Coinciding with the Halving Cycle?
*Author: [Darko](https://mp.weixin.qq.com/s/Po0eyWI4ZktrG0iuYBJ3XA), IOSG Ventures*
Since 1950, the United States has held 19 midterm elections. According to our statistics, one year after each election, the S&P 500 index has always been higher than on the day of voting. Bitcoin has gone through three complete midterm election cycles, and its price one year later has also been higher, but it has experienced a decline in the weeks following each vote.
On November 3 this year, the positions of the two markets are somewhat different. U.S. stocks are close to historical highs, while Bitcoin is still recovering from a significant sell-off in the previous period. Historically, the performance of both can be somewhat optimistic one year later, but the intermediate trends may vary greatly.
However, the reference value of this historical data for 2026 remains questionable. In the year before past midterm elections, the median maximum drawdown for U.S. stocks was 16%, while this year it is only around 9%, meaning there is not much decline to recover. Bitcoin has only three samples, and each midterm election has occurred between two to two and a half years after a halving, making it difficult to determine how much the rise is related to the election itself.
### **Core Views**
* **U.S. Stocks**: Historically, the performance after midterm elections has been quite strong, but this year's pre-election market performance is also stronger than in previous years. Therefore, directly assuming that historical average gains will repeat is not prudent.
* **Bitcoin**: The one-year returns from three complete cycles are all positive, but they have all experienced further declines first. Relying solely on three samples, it is still impossible to confirm the existence of a reliable "election effect."
* **Policy**: Congressional control will affect legislation and regulation in the crypto industry. However, the core factors determining market direction remain corporate earnings, interest rates, and capital flows.
### I. U.S. Stocks: Historical Performance is Bright, but This Year's Starting Point is Different
From 1950 to 2022, there have been 19 midterm elections. In the 12 months following each election, the S&P 500 index recorded gains, with an average increase of 15.1% and a median of 14.5%. Even the weakest performance saw an increase of 1.1%.
In contrast, in non-midterm election years, if we also take early November as the starting point, the average return in the following year is 7.2%, with about 70% of samples recording gains.
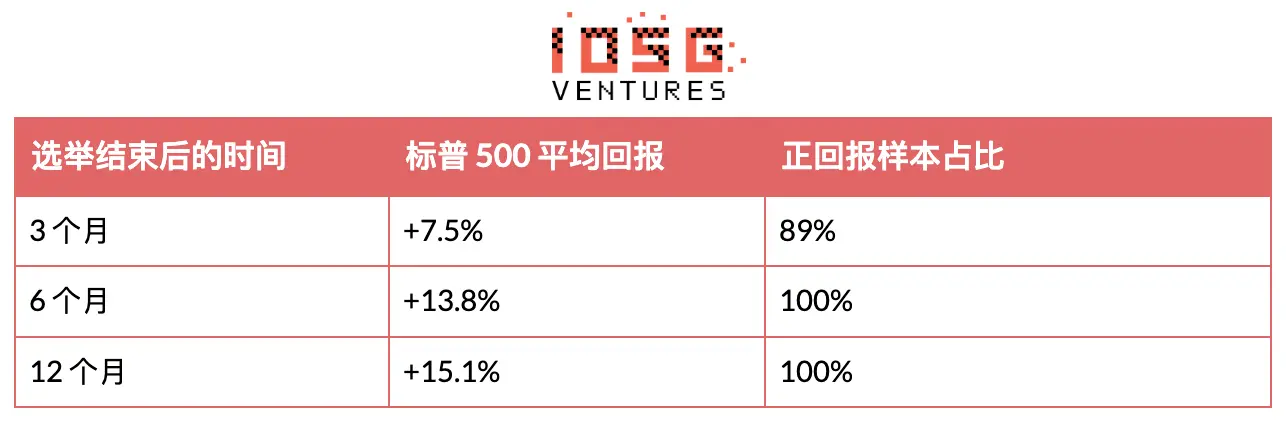
*▲ Source: IOSG, calculated based on daily closing prices*
Historically, declines mostly occurred before elections. In the year before midterm elections, the median maximum drawdown for the market was 16%. Within the six-month observation window set around the voting day, the market low occurred before the voting day in 17 out of 19 elections.
Gains also often do not have to wait until after the voting ends to begin. Analysis from BlackRock shows that as election results become clearer, U.S. stocks typically start to rise about a month before midterm elections. In late October this year, the predicted probability of the Democratic Party controlling the House of Representatives was about 93%, and the probability of controlling the Senate was about 68%. This means that the situation where the president and Congress belong to different parties has been widely anticipated by the market and may not be an unexpected outcome on election day.
This does not mean that all policy impacts have been reflected in prices, but expected results may trigger smaller immediate market reactions than unexpected results. Therefore, election day can serve as a reference point for observing market trends, but it may not necessarily be a turning point.
This year's market starting point is also different. In late October, the S&P 500 index was only about 3% away from the historical closing high set on October 6, while the maximum drawdown in the previous year was about 9%. In other words, there is not much ground for the market to recover.
Historically, there have been five midterm elections that met two conditions: an increase of over 10% before the election and a drawdown of less than 10%. These occurred in 1954, 1958, 1986, 2006, and 2014. The returns in the following year ranged from 1.1% to 33.2%, with a median of 6.7%.
Compared to the seemingly precise median number, this broad range is more noteworthy. These cases illustrate that a strong market may continue to rise after elections, but this is not sufficient to set a reliable return target for 2027.
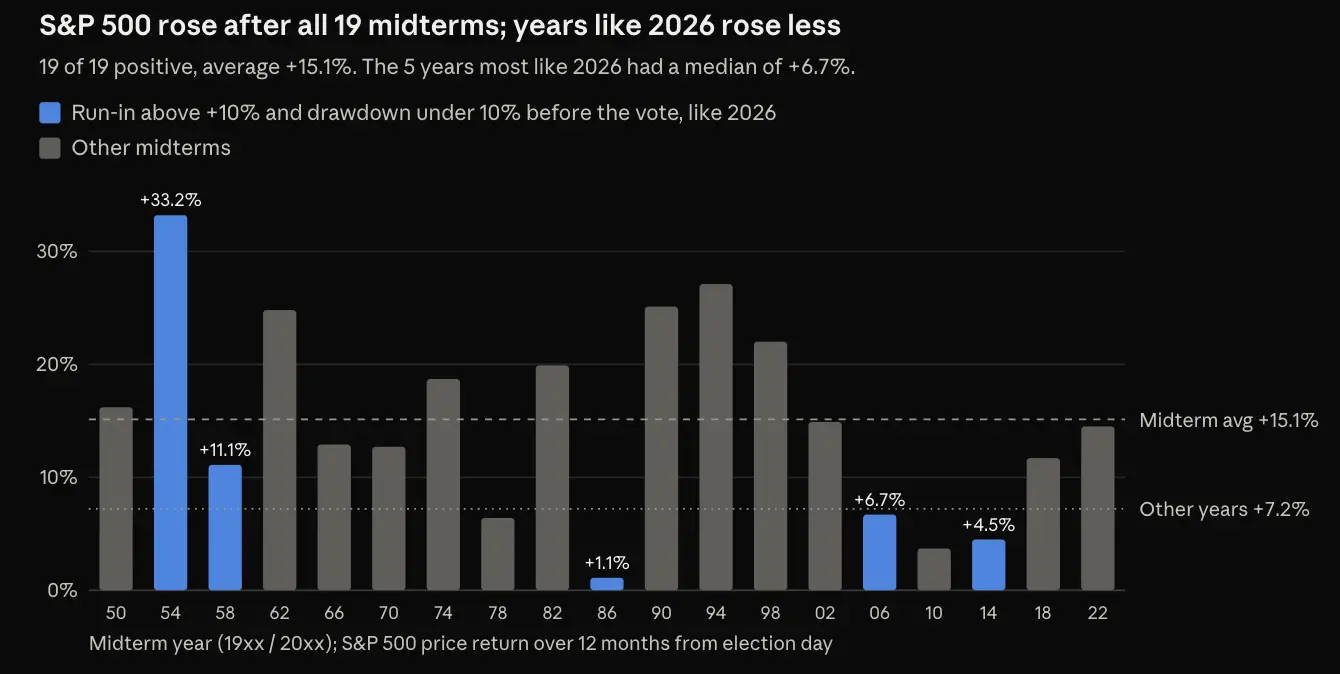
*▲ **Figure 1.** S&P 500 index returns in the 12 months following each midterm election. The blue bars highlight five historical cases that meet the "large pre-election increase and shallow drawdown" conditions for comparison with 2026.*
**Historical experience leans towards optimism, but the next round of increases still requires support from corporate earnings and the interest rate environment.**
### II. Bitcoin: An Increase One Year Later Does Not Mean the Recovery Process is Easy
Bitcoin has a shorter history, and the holding process is also more difficult.
In the three complete midterm election cycles of 2014, 2018, and 2022, BTC experienced declines in the weeks following the voting day, but the price one year later was higher than on the election day. The decline in 2022 was shorter, and by three months post-election, BTC had recorded gains. The short-term performance of the three cycles varies greatly.
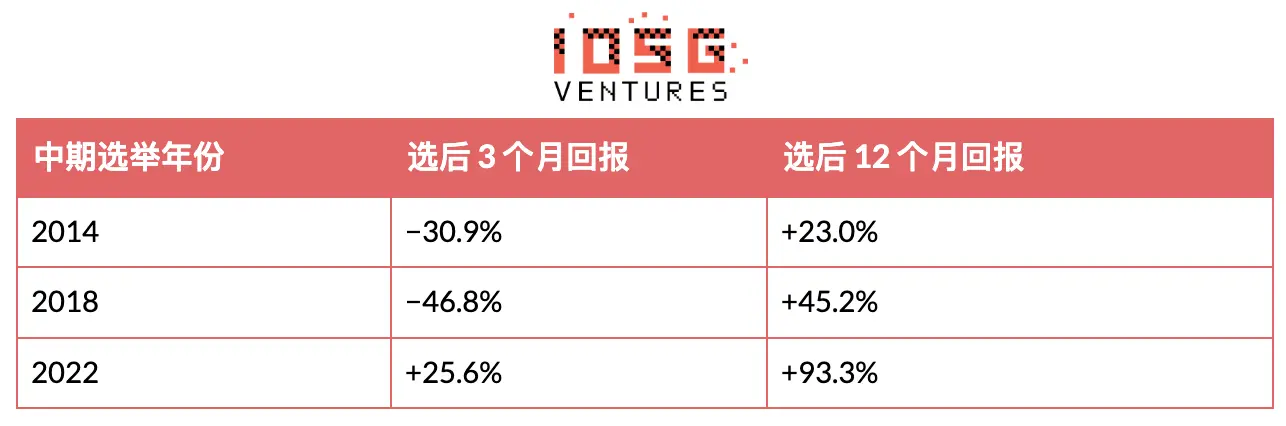
▲ IOSG, calculated using CoinMetrics BTC PriceUSD data
Binance Research points out that the average increase of Bitcoin within one year after midterm elections is about 54%, which is basically consistent with our sample's average increase of 53.8%. However, the process of rising is equally important: the median return in the three months post-election is about -31%, while it is about +45% after twelve months. Even if investors ultimately see the correct recovery direction, they may still endure considerable losses before the rise arrives.
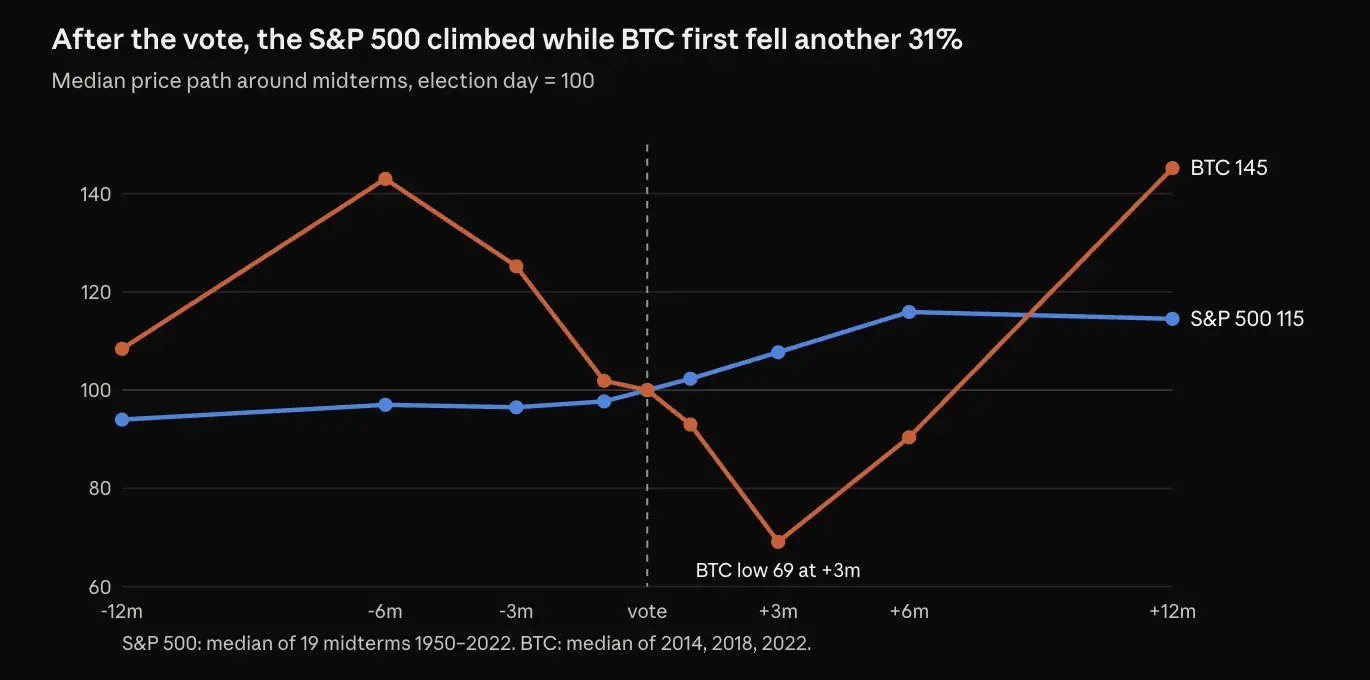
*▲ **Figure 2.** Median performance before and after midterm elections, with the voting day as the reference point, and the index set to 100. The S&P 500 sample covers 19 elections from 1950 to 2022; the Bitcoin sample covers three elections from 2014 to 2022. The lines in the figure only connect selected observation points and do not represent predictions.*
However, these samples cannot independently identify the impact of the election itself. Each midterm election has coincidentally occurred about two to two and a half years after a Bitcoin halving and has been in a bear market phase. The election in November 2026 will also be about two and a half years after the halving in April 2024.
With only three samples and two overlapping cycles, it is impossible to determine whether the election has had a substantial impact on this pattern.
Similarly, the median curve should not be treated as a price prediction. This curve summarizes results from different years and does not represent the complete market experience that investors have actually gone through in a particular cycle. Mechanically applying it to today's prices will only create a sense of precision that the data itself cannot support.
With the entry of spot ETFs and corporate treasury funds, the investor structure of Bitcoin has also changed. These channels can bring demand but may also transmit redemption pressure, financing pressure, and changes in risk appetite to the market.
**What is truly worth remembering is: being optimistic about the performance in the coming year does not contradict the possibility of further short-term declines. As for when the decline will end, historical samples do not provide an answer.**
### **III. What Changes Can Elections Bring to the Crypto Industry?**
For the crypto industry, the most direct impact of elections comes from policy. In a situation where the market generally expects the president and Congress to belong to different parties, it is more important to pay attention to how the new Congress will adjust legislation, regulatory oversight, and personnel appointments in regulatory agencies.
The progress of the CLARITY Act reflects this uncertainty. On September 15, the Senate failed to pass a procedural motion to end debate and advance the bill with a vote of 49 in favor and 50 against. Subsequently, the Senate proposed a motion for reconsideration, so the bill is currently stalled and has not completely lost the chance for a restart. However, before the election recess, the Senate did not hold a second vote, and the only remaining window for this Congress is the "lame duck session" after the election and before the new Congress takes office.
The next Congress will decide the leadership of each committee, legislative priorities, and the specific conditions for renegotiation.
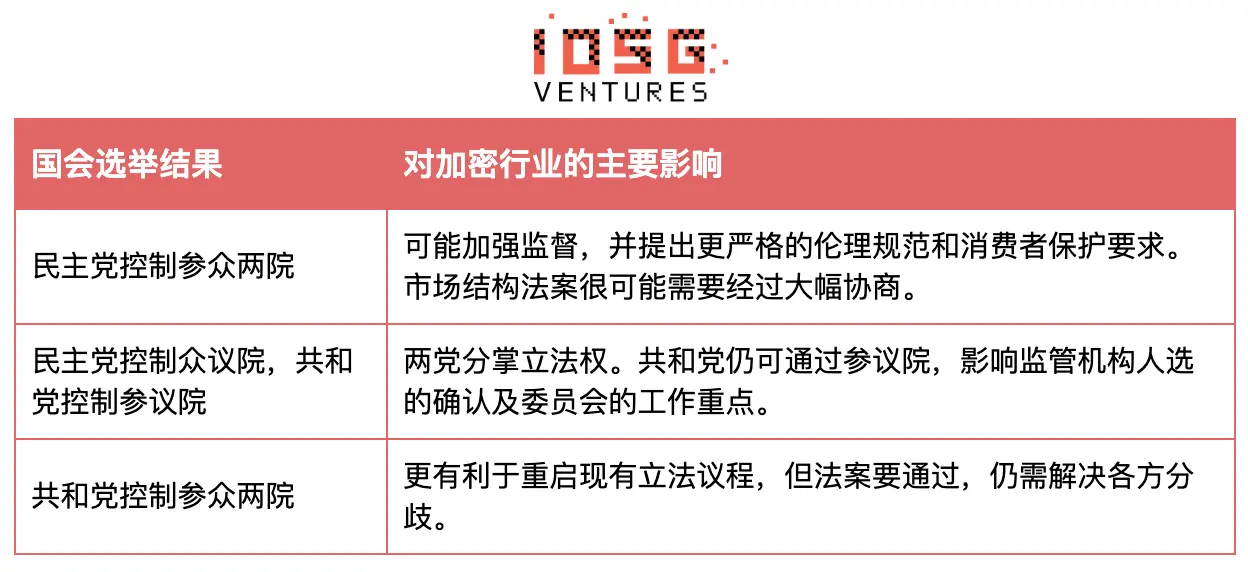
*▲ The above is a scenario analysis, not a prediction of legislative outcomes*
If the Republican Party retains control of the Senate, it may be more favorable for promoting industry-preferred policy proposals, but it does not guarantee the passage of bills. Similarly, if the Democratic Party controls Congress, it does not mean that bipartisan cooperation on legislation is impossible.
At the same time, regulatory agencies can still take action within their existing authority. Establishing rules and issuing staff guidance may help resolve some specific issues, but their applicability and durability may not match that of formal legislation.
The same election outcome may influence U.S. stocks and the crypto industry through different channels. If the president and Congress belong to different parties, new fiscal spending plans may be constrained, alleviating some upward pressure on bond yields and supporting stock valuations. However, for crypto companies, legislative gridlock may also prolong the uncertainty period of market structure rules.
This could lead to a divergence: financial markets welcome constraints on fiscal spending, while the crypto industry may be disappointed by the prolonged wait for a stable legal framework. Of course, neither outcome is inevitable; even if Congress is gridlocked, the executive branch and regulatory agencies may still push for policy changes.
### IV. What Factors Can Support the Market's Continued Rise to 2027?
My baseline judgment is that the outlook for U.S. stocks is generally optimistic, but the upward process will have twists and turns; the short-term trend of Bitcoin is harder to judge. This judgment is made after referencing history and is not a prediction directly derived from historical data.
For U.S. stocks, continuous growth in corporate earnings and alleviation of pressure from bond yields will help the market rise further. If the upward momentum can spread from large tech companies to more companies, the recovery will be more convincing. Conversely, regardless of which party controls Congress, persistent high inflation or earnings falling short of expectations will weaken the bullish rationale.
For Bitcoin, I will pay attention to whether spot ETFs can continue to attract funds, whether liquidity improves, and whether Bitcoin can maintain its previous gains when the overall market weakens. If funds continue to flow out or financing pressure rises again, it would not be wise to easily conclude that the bear market low has passed.
The following three changes are particularly worth noting:
* **The Federal Reserve's meeting on December 8-9**: The Federal Reserve maintained interest rates at 3.75%-4.00% on October 28, with two members voting against it, and the market has begun to factor in the possibility of a rate hike in December. New economic forecasts will help determine whether the pressure from bond yields is easing.
* **Profit and Upward Coverage**: Whether profit growth and stock price increases can spread from the currently leading companies in the index to more enterprises.
* **Bitcoin Capital Flow**: Whether institutional demand can be maintained for several consecutive weeks, rather than being concentrated on individual trading days.
Election results should be observed alongside these indicators and cannot replace them.
### Conclusion
The most compelling finding in historical data is the high consistency of the U.S. stock market's continued rise after midterm elections. However, it should also be noted that the stock market is already quite strong before the 2026 vote.
The insights provided by Bitcoin are different: in three complete cycles, the price one year later is always higher, but investors have also experienced further declines. This helps to understand the risks of holding but is insufficient to support a clear prediction for the next cycle.
The election on November 3 will impact the future policy environment. Whether the market can continue its recovery in 2027 ultimately depends on subsequent corporate earnings, liquidity, and capital flows.
### **Main References**
* **BlackRock------How History Views the 2026 Midterm Elections and Market Performance**
https://www.blackrock.com/us/financial-professionals/insights/2026-midterm-elections-and-market-performance?utm_source=chatgpt.com
* **Edward Jones------Midterm Elections and the Market: Historical Lessons and Current Considerations**
https://www.edwardjones.com/us-en/market-news-insights/stock-market-news/market-pulse/midterms-markets-lessons-history-considerations-today?utm_source=chatgpt.com
* **Binance Research Weekly------Minefields, Midterm Election Cycles, and Asymmetric Opportunities**
https://www.binance.com/research/analysis/weekly-market-commentary-2026-03-11?utm_source=chatgpt.com
* **U.S. Senate------September 15, 2026, Proceedings and Vote on the CLARITY Act**
https://www.dailypress.senate.gov/tuesday-september-15-2026/?utm_source=chatgpt.com
* **Federal Reserve------Federal Open Market Committee Meeting Schedule**
https://www.federalreserve.gov/monetarypolicy/fomccalendars.htm?utm_source=chatgpt.com
* **Polymarket------Power Dynamics of the 2026 Midterm Elections**
https://polymarket.com/event/balance-of-power-2026-midterms?utm_source=chatgpt.com
* **Troutman Pepper Locke------In the Wake of the CLARITY Act's Failure, Agencies Continue to Move Forward Without Congressional Action or Certainty Amid Uncertain Policies**
https://www.troutman.com/insights/in-the-wake-of-clarity-acts-failure-agencies-move-forward-without-congressional-action-or-certainty/?utm_source=chatgpt.com
*Historical tables and charts: IOSG uses Yahoo Finance S&P 500 daily closing prices (^GSPC, excluding dividends) and CoinMetrics BTC PriceUSD data for calculations.*